

€ 59,99 Gratis verzending

Uitgelicht
|
|
59,99 |
Naar shop
|

|
59,99 |
Naar shop
|

|
59,99 |
Naar shop
|
| VERGELIJK ALLE AANBIEDERS (3) | ||
 Beschrijving
Vergelijk aanbieders (3)
€ 59,99 Gratis verzending
€ 59,99 Gratis verzending
€ 59,99 Gratis verzending
Winkels met andere maten
Beschrijving
(1)
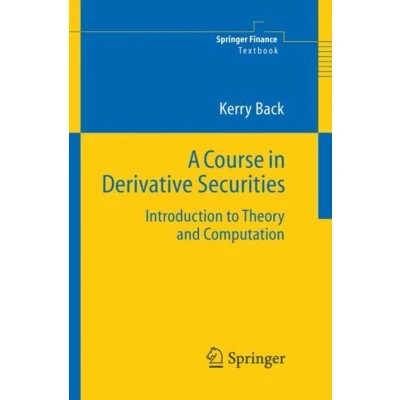
It provides derivations of pricing and hedging formulas (using the probabilistic change of numeraire technique) for standard options, exchange options, options on forwards and futures, quanto options, exotic options, caps, floors and swaptions, as well as VBA code implementing the formulas. This book aims at a middle ground between the introductory books on derivative securities and those that provide advanced mathematical treatments. It is written for mathematically capable students who have not necessarily had prior exposure to probability theory, stochastic calculus, or computer programming. It provides derivations of pricing and hedging formulas (using the probabilistic change of numeraire technique) for standard options, exchange options, options on forwards and futures, quanto options, exotic options, caps, floors and swaptions, as well as VBA code implementing the formulas. It also contains an introduction to Monte Carlo, binomial models, and finite-difference methods. This book aims at a middle ground between the introductory books on derivative securities and those that provide advanced mathematical treatments. It is written for mathematically capable students who have not necessarily had prior exposure to probability theory, stochastic calculus, or computer programming. It provides derivations of pricing and hedging formulas (using the probabilistic change of numeraire technique) for standard options, exchange options, options on forwards and futures, quanto options, exotic options, caps, floors and swaptions, as well as VBA code implementing the formulas. It also contains an introduction to Monte Carlo, binomial models, and finite-difference methods.
 Prijshistorie
* Prijshistorie bevat geen data van Amazon, Amazon Marketplace.
Prijzen voor het laatst bijgewerkt op:
 Gerelateerde resultaten
 Productspecificaties


