

€ 48,90 Gratis verzending

Gesponsorde links
|
|
48,90 |
Naar shop
|

|
48,90 |
Naar shop
|
|
48,90 |
Naar shop
|
| VERGELIJK ALLE AANBIEDERS (3) | ||
 Beschrijving
Vergelijk aanbieders (3)
Gesponsorde links · Sommige shops betalen ons een vergoeding
€ 48,90 Gratis verzending
€ 48,90 Gratis verzending
€ 48,90 Gratis verzending
Winkels met andere maten
Beschrijving
(1)
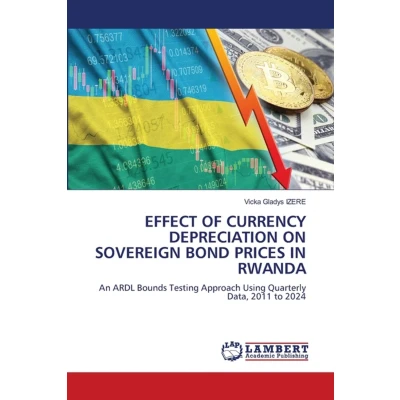
This book examines how currency depreciation affects sovereign bond prices in Rwanda, using quarterly data spanning 2011 to 2024 drawn from the National Bank of Rwanda, the Rwanda Stock Exchange, the IMF, and the World Bank. Despite the persistent weakening of the Rwandan franc against the US dollar and the growing role of domestic bonds in financing national development, no earlier study had jointly quantified the channels linking exchange rate movements to bond prices in Rwanda. The analysis centers on the USD/RWF exchange rate, the Central Bank Rate, and money market liquidity as transmission mechanisms, controlling for inflation and bond maturity. Using an Autoregressive Distributed Lag (ARDL) bounds testing approach, the study finds that exchange rate depreciation has no significant direct effect on bond prices, but works indirectly through the monetary policy channel: the Central Bank Rate has a significant negative effect on prices in both the short and long run, while money market liquidity matters mainly in the short run. The findings offer practical guidance for policymakers, debt managers, frontier bond markets.
 Prijshistorie
* Prijshistorie bevat geen data van Amazon, Amazon Marketplace.
Prijzen voor het laatst bijgewerkt op:
 Gerelateerde resultaten
 Productspecificaties


