

€ 31,67 Gratis verzending

Gesponsorde links
|
|
31,67 |
Naar shop
|

|
32,95 |
Naar shop
|

|
32,95 |
Naar shop
|
| VERGELIJK ALLE AANBIEDERS (3) | ||
 Beschrijving
Vergelijk aanbieders (3)
Gesponsorde links · Sommige shops betalen ons een vergoeding
€ 31,67 Gratis verzending
€ 32,95 Gratis verzending
€ 32,95 Gratis verzending
Winkels met andere maten
Beschrijving
(1)
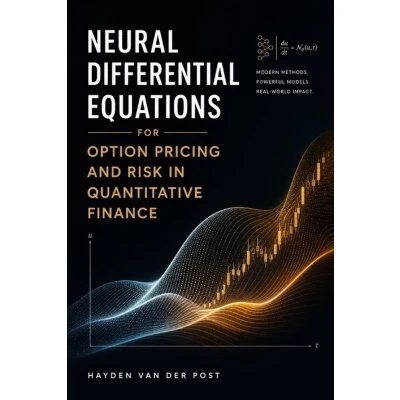
Reactive PublishingNeural Differential Equations for Option Pricing and Risk in Quantitative Finance presents a focused treatment of continuous-time neural models and their application to core problems in quantitative finance.The book examines how neural ordinary and stochastic differential equations can be used to model asset-price dynamics, calibrate to market data, and address option pricing and risk-management tasks. It covers the mathematical foundations of neural differential equations, their relationship to classical stochastic processes, and practical considerations for implementing these models in a financial setting.Topics include the construction and training of neural SDEs, no-arbitrage constraints, calibration to option surfaces, and the use of continuous-time models for risk measures and hedging. Emphasis is placed on clarity of formulation, numerical stability, and the connection between the continuous-time framework and discrete market observations.This work is intended for quantitative analysts, researchers, and advanced practitioners who already possess a working knowledge of stochastic calculus, option pricing theory, and machine-learning methods, and who wish to understand the specific role of neural differential equations in modern quantitative finance.
 Prijshistorie
* Prijshistorie bevat geen data van Amazon, Amazon Marketplace.
Prijzen voor het laatst bijgewerkt op:
 Gerelateerde resultaten
 Productspecificaties


