

€ 41,53 Gratis verzending

Gesponsorde links
|
|
41,53 |
Naar shop
|

|
41,53 |
Naar shop
|
|
43,99 |
Naar shop
|
| VERGELIJK ALLE AANBIEDERS (3) | ||
 Beschrijving
Vergelijk aanbieders (3)
Gesponsorde links · Sommige shops betalen ons een vergoeding
€ 41,53 Gratis verzending
€ 41,53 Gratis verzending
€ 43,99 Gratis verzending
Winkels met andere maten
Beschrijving
(1)
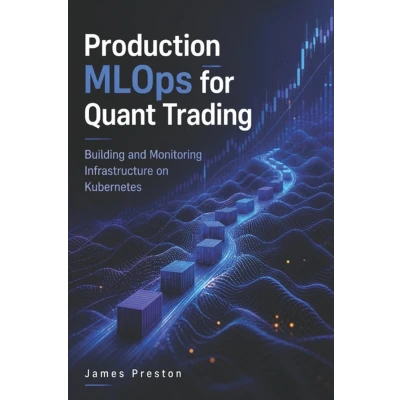
Reactive PublishingBuild, deploy, and scale institutional-grade machine learning pipelines designed specifically for high-frequency and quantitative trading environments.In quantitative finance, model latency, feature staleness, and unmonitored drift directly translate to financial loss. Production MLOps for Quant Trading delivers a practical, hands-on blueprint for building resilient, continuous-delivery ML systems on Kubernetes-tailored to the zero-tolerance demands of live market execution.This book skips theoretical high-level overviews to focus on the concrete engineering challenges quant developers, MLOps engineers, and financial data scientists face daily: - Automated CI/CD Pipelines: Design and execute robust testing, validation, and deployment automation for live algorithmic models.- Low-Latency Feature Stores: Implement real-time and batch feature management to eliminate training-serving skew in dynamic markets.- Model Drift & Anomaly Detection: Detect concept drift, covariate shift, and signal decay before bad trades execute.- Kubernetes Infrastructure: Orchestrate distributed training, auto-scaling, and self-healing workloads on enterprise cloud environments.Packed with production-ready architectures, actionable code patterns, and real-world trade-offs, this guide provides the exact technical roadmap needed to bridge the gap between backtested alpha and live trading execution.
 Prijshistorie
* Prijshistorie bevat geen data van Amazon, Amazon Marketplace.
Prijzen voor het laatst bijgewerkt op:
 Gerelateerde resultaten
 Productspecificaties


