
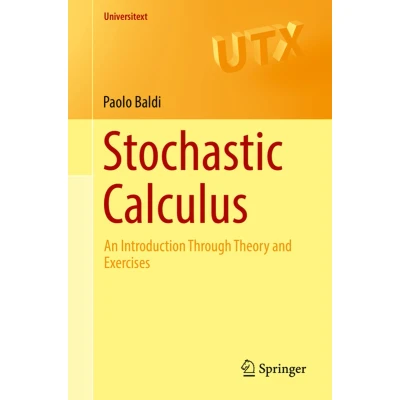
Stochastic Calculus
Uitgelicht

|
86,97 |
Naar shop
|

|
86,97 |
Naar shop
|
|
99,99 |
Naar shop
|
| VERGELIJK ALLE AANBIEDERS (3) | ||
 Beschrijving
Bol
The core of the book covers stochastic calculus, including stochastic differential equations, the relationship to partial differential equations, numerical methods and simulation, as well as applications of stochastic processes to finance. This book provides a comprehensive introduction to the theory of stochastic calculus and some of its applications. It is the only textbook on the subject to include more than two hundred exercises with complete solutions. After explaining the basic elements of probability, the author introduces more advanced topics such as Brownian motion, martingales and Markov processes. The core of the book covers stochastic calculus, including stochastic differential equations, the relationship to partial differential equations, numerical methods and simulation, as well as applications of stochastic processes to finance. The final chapter provides detailed solutions to all exercises, in some cases presenting various solution techniques together with a discussion of advantages and drawbacks of the methods used. Stochastic Calculus will be particularly useful to advanced undergraduate and graduate students wishing to acquire a solid understanding of the subject through the theory and exercises. Including full mathematical statements and rigorous proofs, this book is completely self-contained and suitable for lecture courses as well as self-study. This book provides a comprehensive introduction to the theory of stochastic calculus and some of its applications. It is the only textbook on the subject to include more than two hundred exercises with complete solutions. After explaining the basic elements of probability, the author introduces more advanced topics such as Brownian motion, martingales and Markov processes. The core of the book covers stochastic calculus, including stochastic differential equations, the relationship to partial differential equations, numerical methods and simulation, as well as applications of stochastic processes to finance. The final chapter provides detailed solutions to all exercises, in some cases presenting various solution techniques together with a discussion of advantages and drawbacks of the methods used. Stochastic Calculus will be particularly useful to advanced undergraduate and graduate students wishing to acquire a solid understanding of the subject through the theory and exercises. Including full mathematical statements and rigorous proofs, this book is completely self-contained and suitable for lecture courses as well as self-study.


 Beschrijving
(1)
The core of the book covers stochastic calculus, including stochastic differential equations, the relationship to partial differential equations, numerical methods and simulation, as well as applications of stochastic processes to finance. This book provides a comprehensive introduction to the theory of stochastic calculus and some of its applications. It is the only textbook on the subject to include more than two hundred exercises with complete solutions. After explaining the basic elements of probability, the author introduces more advanced topics such as Brownian motion, martingales and Markov processes. The core of the book covers stochastic calculus, including stochastic differential equations, the relationship to partial differential equations, numerical methods and simulation, as well as applications of stochastic processes to finance. The final chapter provides detailed solutions to all exercises, in some cases presenting various solution techniques together with a discussion of advantages and drawbacks of the methods used. Stochastic Calculus will be particularly useful to advanced undergraduate and graduate students wishing to acquire a solid understanding of the subject through the theory and exercises. Including full mathematical statements and rigorous proofs, this book is completely self-contained and suitable for lecture courses as well as self-study. This book provides a comprehensive introduction to the theory of stochastic calculus and some of its applications. It is the only textbook on the subject to include more than two hundred exercises with complete solutions. After explaining the basic elements of probability, the author introduces more advanced topics such as Brownian motion, martingales and Markov processes. The core of the book covers stochastic calculus, including stochastic differential equations, the relationship to partial differential equations, numerical methods and simulation, as well as applications of stochastic processes to finance. The final chapter provides detailed solutions to all exercises, in some cases presenting various solution techniques together with a discussion of advantages and drawbacks of the methods used. Stochastic Calculus will be particularly useful to advanced undergraduate and graduate students wishing to acquire a solid understanding of the subject through the theory and exercises. Including full mathematical statements and rigorous proofs, this book is completely self-contained and suitable for lecture courses as well as self-study.
 Productspecificaties
 Prijshistorie
* Prijshistorie bevat geen data van Amazon, Amazon Marketplace.
Prijzen voor het laatst bijgewerkt op:
 Gerelateerde resultaten


