

€ 46,99 Gratis verzending

Uitgelicht
|
|
46,99 |
Naar shop
|

|
69,58 |
Naar shop
|

|
69,58 |
Naar shop
|
| VERGELIJK ALLE AANBIEDERS (3) | ||
 Beschrijving
Vergelijk aanbieders (3)
€ 46,99 Gratis verzending
€ 69,58 € 4,16 verzendkosten Totaal € 73,74
€ 69,58 € 4,16 verzendkosten Totaal € 73,74
Winkels met andere maten
Beschrijving
(1)
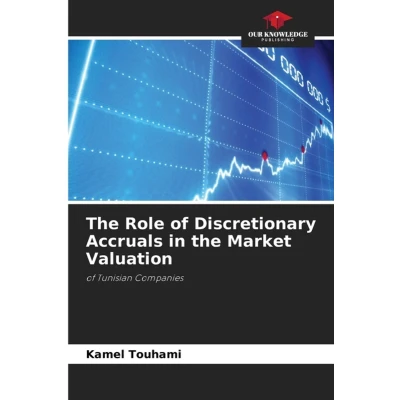
Based on a sample of Tunisian companies, we sought to demonstrate that discretionary accruals provide additional information relative to other components of earnings. The association analysis showed that, on the one hand, aggregate net income better explains stock market returns than operating cash flows, contrary to the findings prior to the reform. On the other hand, disaggregating net income improves explanatory power. In particular, it appears that investors view discretionary accruals positively, indicating that earnings management produces an accounting measure of corporate performance that is more consistent with the performance as perceived by the Tunisian financial market.
 Prijshistorie
* Prijshistorie bevat geen data van Amazon, Amazon Marketplace.
Prijzen voor het laatst bijgewerkt op:
 Gerelateerde resultaten
 Productspecificaties


